Hard Money Lender Paths for Fast Fix and Flip Loans
Need speed on a renovation buy? A hard money lender can fund fix and flip loans on asset strength and exit plan rather than slow bank underwriting. CapitalFlow Solution structures short-term capital so informed investors can lock deals, start work, and recycle equity without waiting on conventional credit cycles.
Key takeaways
- Fix and flip loans prioritize collateral, timeline, and resale math over lengthy income docs.
- Fast closings hinge on clear scope, ARV realism, and a defined exit.
- Bridge-style terms can cover acquisition plus rehab when banks stall.
- Local practitioner review cuts surprises before you wire earnest money.
How do fix and flip loans work with asset-based funding?
Fix and flip loans from asset-based lenders size advances to purchase price and rehab budget against after-repair value, with interest and points priced for short holds so you can buy, renovate, and sell or refinance without multi-month bank conditions. Terms track your schedule; draw schedules match verified progress. Pair this path with how bridge loans help investors secure properties faster when timing is tight.
Which hard money lender structure fits your fix and flip timeline?
A hard money lender typically prices fix and flip loans around collateral, rehab scope, and exit speed, so you choose short holds with draws when the flip is clear, longer interest reserves when permits drag, higher leverage when ARV is conservative, or acquisition-only when you fund rehab from cash—matching term length and points to your real schedule rather than a bank calendar.
| Option | Best for | Watch-out |
|---|---|---|
| Short-term full package | Fast flips with defined scope and resale | Over-optimistic ARV or thin contingency |
| Interest-reserve hold | Permits, inspections, or slower comps | Carry cost if the market softens |
| Higher LTV on strong ARV | Experienced crews and proven exits | Draw delays if work is not verified |
| Acquisition-first funding | Investors who self-fund rehab phases | Gap risk if cash is tied up elsewhere |
Keep paragraphs tight when you underwrite: purchase, rehab, ARV, and days-to-exit must line up before you bid. The
CapitalFlow Solution approach reviews those numbers with a practitioner lens so points and draws do not surprise you mid-project.
When the deal pencil works and you need a next step, request a term review with your scope, budget, and target close date ready.
Hard Money Lender or Bridge Loan: Which Fits a Fix and Flip?
A hard money lender usually funds purchase plus rehab with draw schedules and points priced to speed, while a bridge loan often covers acquisition or gap capital when you already control rehab cash or need a short runway to refinance; choose the hard money path when the flip scope is clear and resale is the exit, and lean bridge-style terms when timing hinges on a sale or permanent loan rather than construction draws alone.
Match the product to exit, not habit. Fix and flip loans from a hard money lender work when ARV, contractor capacity, and days on market are tight and documented. Bridge structures help when you need to lock title fast and finish funding later. Read how bridge loans help investors secure properties faster if acquisition speed is the bottleneck.
CapitalFlow Solution underwrites both with the same discipline: purchase, rehab budget, ARV, and carry must pencil before points and reserves are set. Ask for draw rules in writing. Confirm inspection triggers. Keep contingency real so a delay does not force a distressed sale.
If your next bid needs a clear term path, bring scope and comps and move from comparison to commitment without padding the calendar.
How draw schedules keep fix and flip loans on track
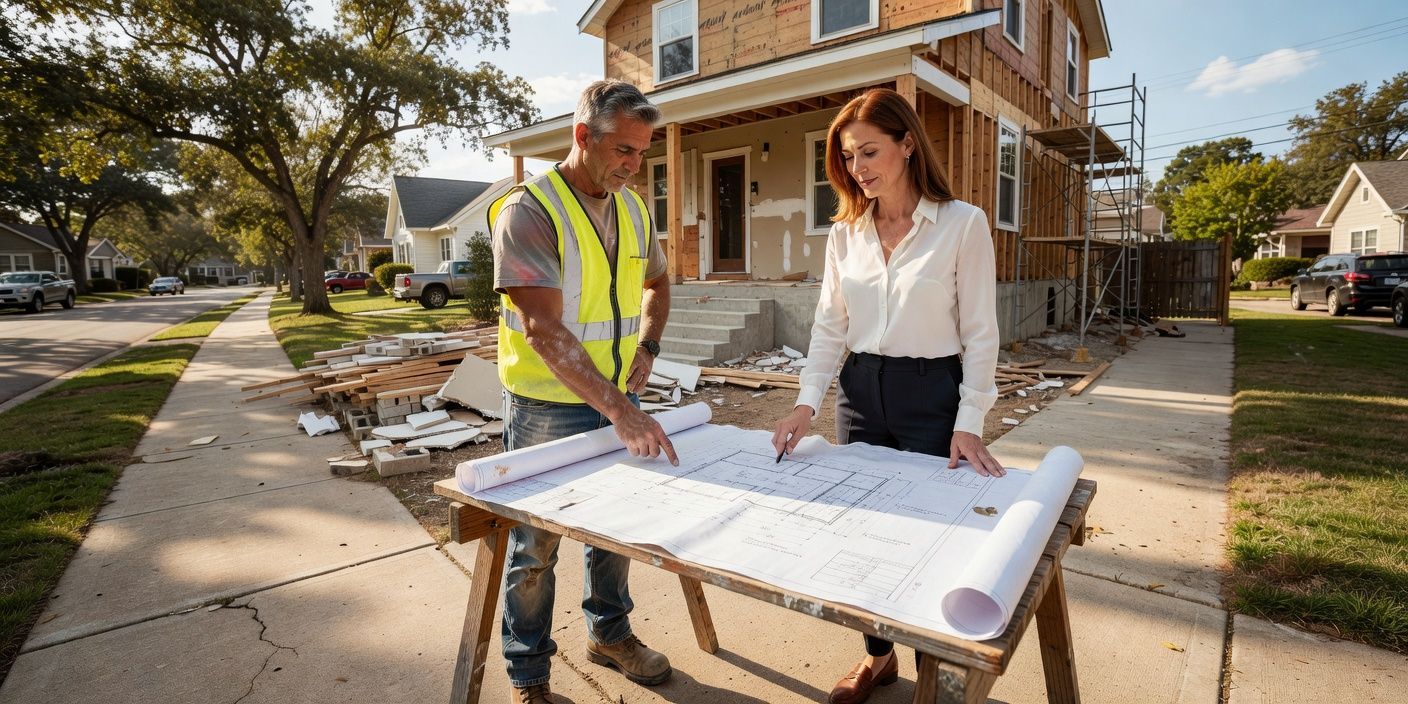
A hard money lender releases rehab funds against verified milestones—photos, invoices, and inspection sign-off—so cash follows completed work rather than forecasts, interest usually runs on the drawn balance, and overruns surface before they erase margin on the resale. That discipline protects both timeline and equity when days on market are short.
Write change orders the same day they arise. Match your GC’s payment schedule to the lender’s draw list so nobody waits on paperwork mid-demo.
When the CapitalFlow Solution method reviews scope, line-item budgets beat round allowances every time.
What to bring before terms are locked
Assemble ARV comps, contractor bids with quantities, title status, and a hold-period plan so points, rate, and reserves fit the exit instead of a generic template. Thin files slow closings more than tough underwriting does.
Ready to price a live address? Send the package through Contact and align draws to your bid window.
Frequently Asked Questions
What does a hard money lender underwrite first on fix and flip loans?
Purchase price, rehab budget, after-repair value, and exit timing come first so the loan amount, points, and reserves reflect real margin. Incomplete scopes or soft comps delay approval more than rate shopping. Document contractor capacity and local days-on-market before you request a term sheet.
How do fix and flip loans differ from longer rental financing?
Fix and flip loans prioritize speed, construction draws, and a resale or refinance exit inside a short term, with pricing built around ARV and carry. Rental products lean on stabilized income and longer amortization. Match product to exit so you are not paying flip pricing on a hold strategy.
When should investors choose a hard money lender over a bank?
Choose a hard money lender when closing speed, flexible credit overlays, and rehab draws matter more than the lowest coupon, especially on value-add flips with clear ARV. Banks often need longer underwriting and tighter occupancy rules. Use private capital when the bid calendar cannot wait on committee cycles.
Preferred Source on Google Search
Add www.capitalflowsolution.com to customize your search feed across Top Stories.